Roof insurance claim documentation is the part that decides the payout, and it takes 20 minutes with a phone. Insurers commonly give you 12 months from the storm to file.
Why documentation decides the claim
A storm damage roof claim turns on evidence created before anything is covered, moved or dried, and it costs nothing to produce.
Roof insurance claim documentation is what turns storm damage into a paid claim: photographs, dates, and a record of what you did to stop the loss. The storm and roof guide covers the damage itself, a leak in heavy rain is often the first sign, and Emergency Services 24H routes storm damage repair to local roofers nearby.
What counts as storm damage
What is considered storm damage depends on the peril, as the Insurance Information Institute explains for standard policies: wind damage, hail damage and impact are covered events on most policies, while granular wear is not.
Photograph granule loss, damaged shingles and any water leaks inside.
Why the adjuster measures
Different types of roof show damage from storm events differently, which is why the adjuster measures rather than eyeballs.
Photograph granule loss, damaged shingles and any water leaks inside. Storm damage roof repair is judged on evidence: what insurance pays turns on what you can show rather than on how the roof looks to you.
Repair or replacement
Storm damage roof insurance coverage differs by peril and by policy age, and whether they pay for roof repair or replacement is the argument most claims turn on.
The signs of storm damage the adjuster looks for are the ones worth photographing first. Different types of roof show damage from storm events differently, which is why a roof storm inspection measures rather than eyeballs.
Photograph before you cover anything
That sequence is the single most consequential thing on this page, and it is missing from the top guides online on storm roof damage.
A fixed order beats a good memory
Four passes, and none of them take long
01
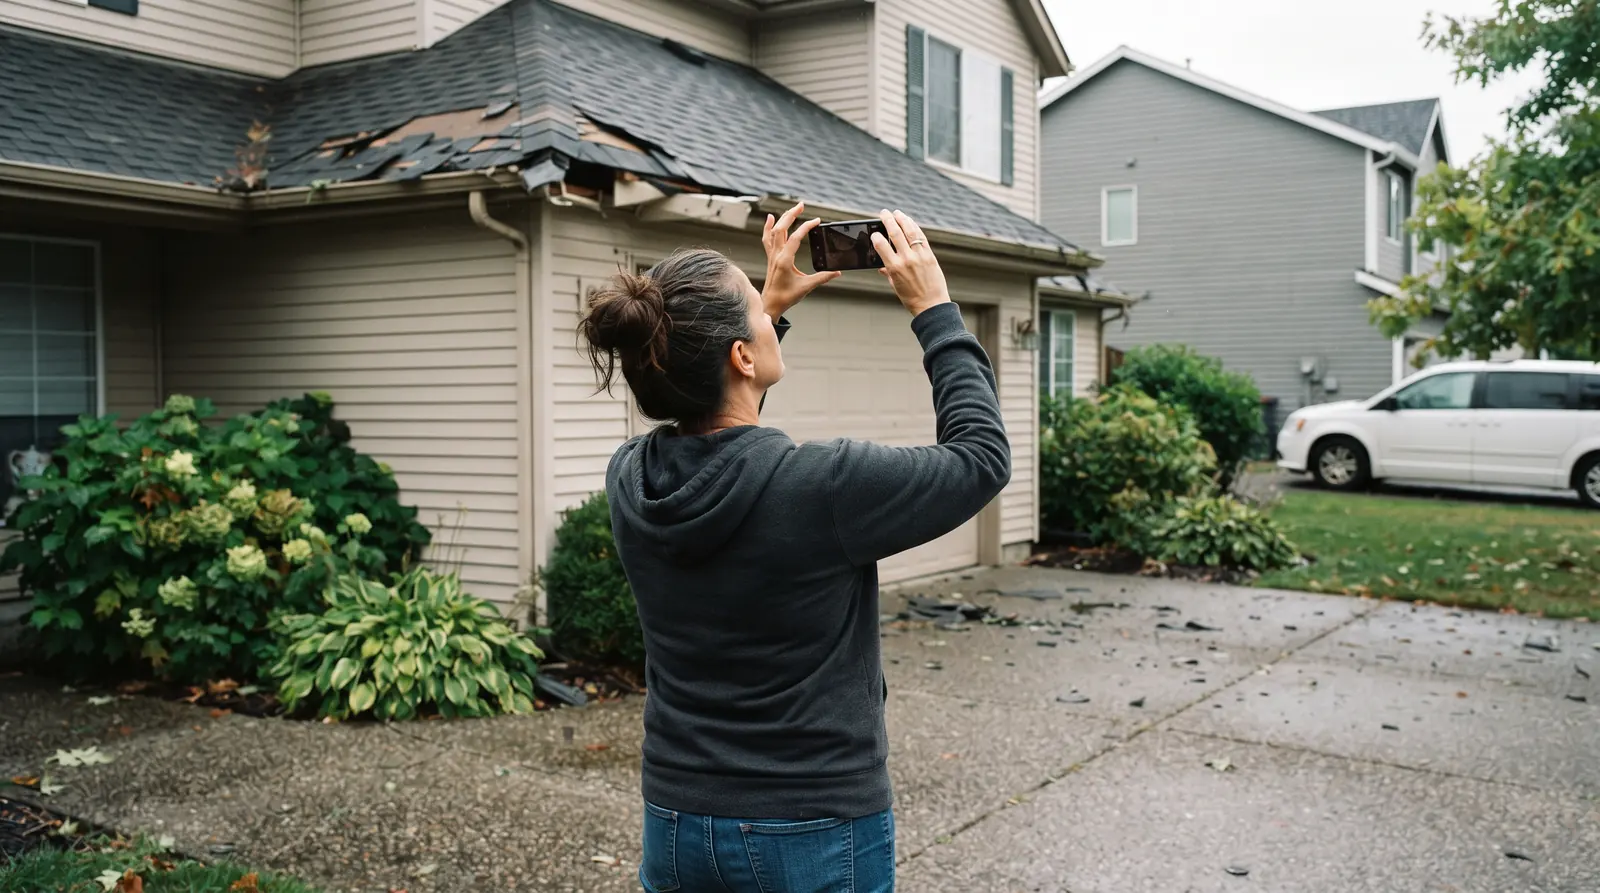
Photograph before you cover anything
Temporary protection changes the evidence permanently. The camera comes out before the tarp goes on, without exception.
02
Work outside in, then up
Elevations, then close damage, then the interior, then the attic. Working in a fixed order stops you finishing with gaps.
03
Write down what photos cannot show
Date, time, the weather event, and a log of every call with names and outcomes. That log is frequently more useful than any single image.
04
Keep every receipt
Tarps, buckets, fans, emergency call-outs and contractor invoices. Reasonable emergency mitigation costs are normally claimable.
Cited source0:23
On phoning your insurer to “just ask” whether storm damage is covered.
“You're filing a claim when you do that.”
HR
Homestead Roofing, Inc
Roofing contractor and inspector, Colorado Springs
Homestead Roofing, Jul 2023
An independent source we cite. Not affiliated with Emergency Services 24H, and not a network contractor.
Wide shots of each elevation, showing the whole roof plane and its context.
Close shots of missing, lifted or creased shingles, from the ground or a window.
Gutters and downspouts, including any accumulated granules.
Vents, flashing and penetrations, plus any visible impact point.
The surroundings: fallen branches, debris, and damage to fences or outbuildings.
Ground level and a zoom lens beat a ladder on a damaged roof. Nothing in this list is worth a fall.
The interior list
Photograph every stained ceiling, wet wall, damaged floor and ruined item inside, with something in frame for scale. Insurers see far more roof photographs than interior ones, and the interior is where the loss actually lands.
Ceiling staining, with a ruler, a coin or a hand for scale.
Damaged contents, flooring and personal property, individually rather than as one wide shot.
Wet insulation anywhere it is visible.
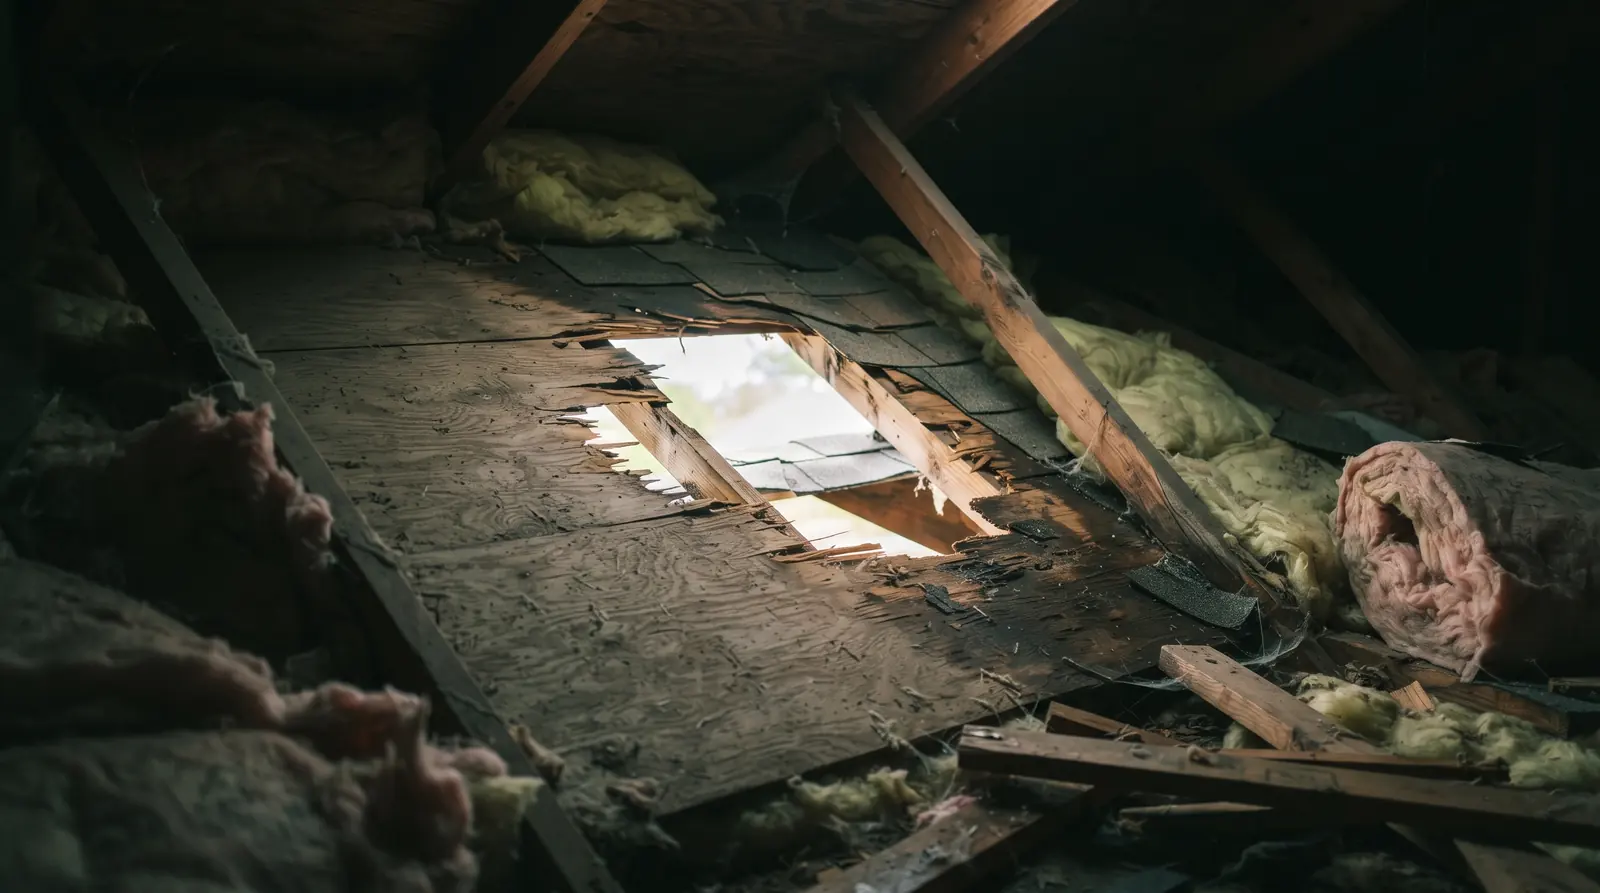
Any daylight visible through the roof structure from inside.
The attic is where the claim is won
Do it before drying equipment runs, because a dry rafter photographed three days later proves considerably less than a wet one photographed today.
What to write down
Write down the date and time of the storm, when you first saw the damage, and every call you make. Photographs establish what. Notes establish when and why, and those are the two things a disputed claim argues about.
Date and time you first noticed each item of damage.
The weather event, including locally reported wind speeds or hail if available.
Every call: who you spoke to, when, what was said and what was agreed.
Anything a contractor tells you about the cause, in their words, ideally in writing.
What to keep
Keep every receipt, because receipts turn into reimbursement, and the ones people throw away are the small ones.
Keep receipts for tarps, buckets, fans, dehumidifier rental and any emergency call-out. Keep the written scope and invoice from every contractor.
Roof insurance claim documentation for the adjuster visit
Have every photo, note and receipt in one folder and walk the roofline with the adjuster. This is the conversation homeowners worry about most, and preparation is most of it.
Have the photographs, notes and receipts in one place before they arrive. Walk the property with them rather than waiting inside, because you know where the water went and they do not.
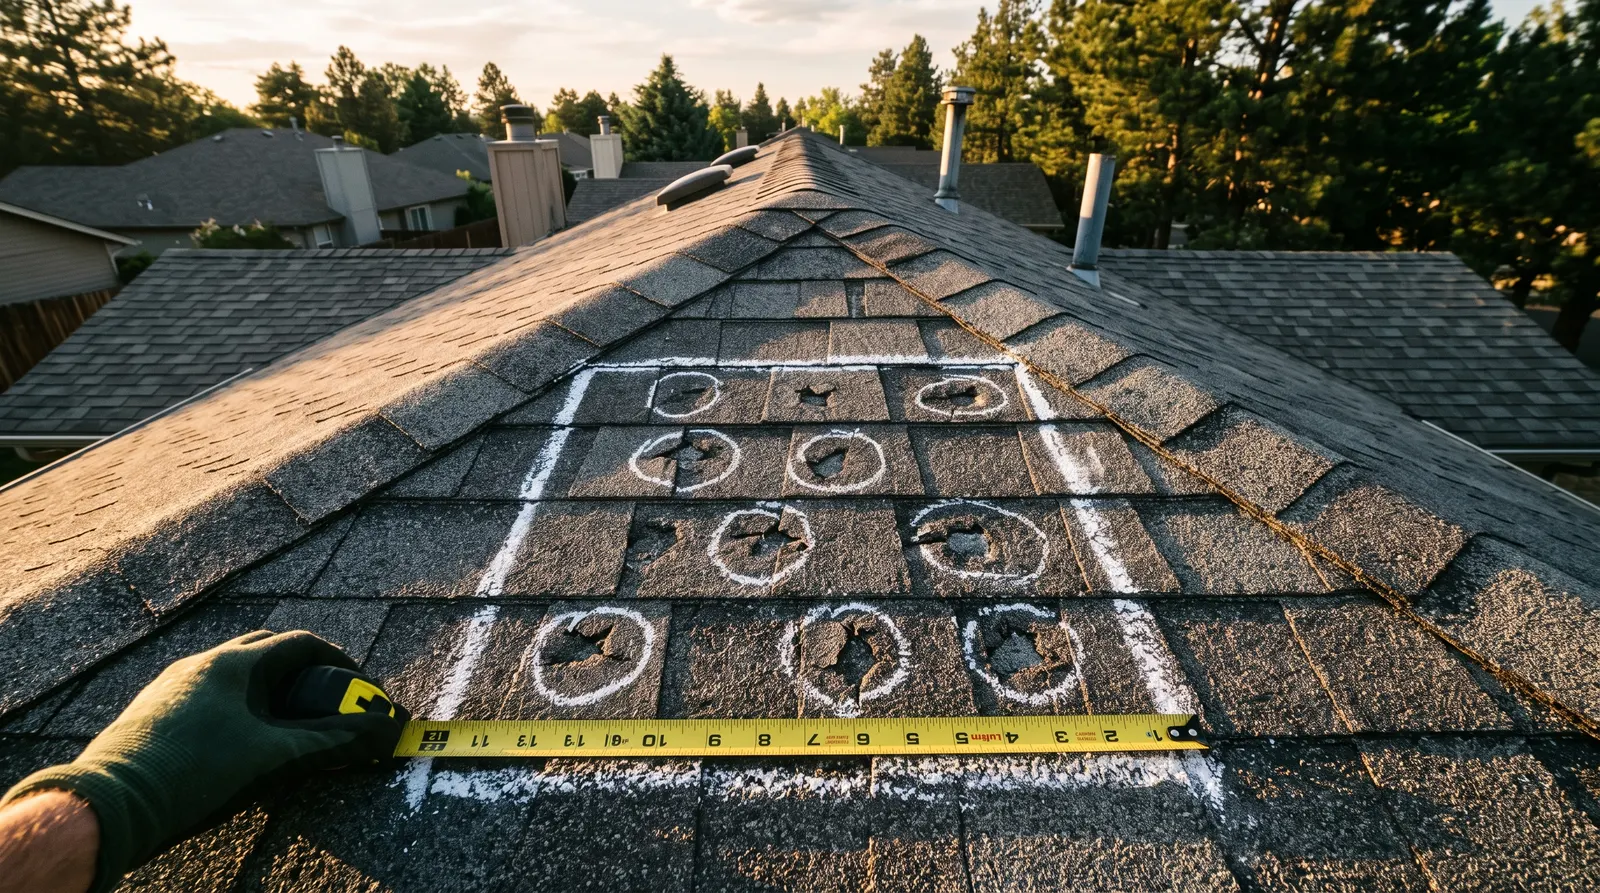
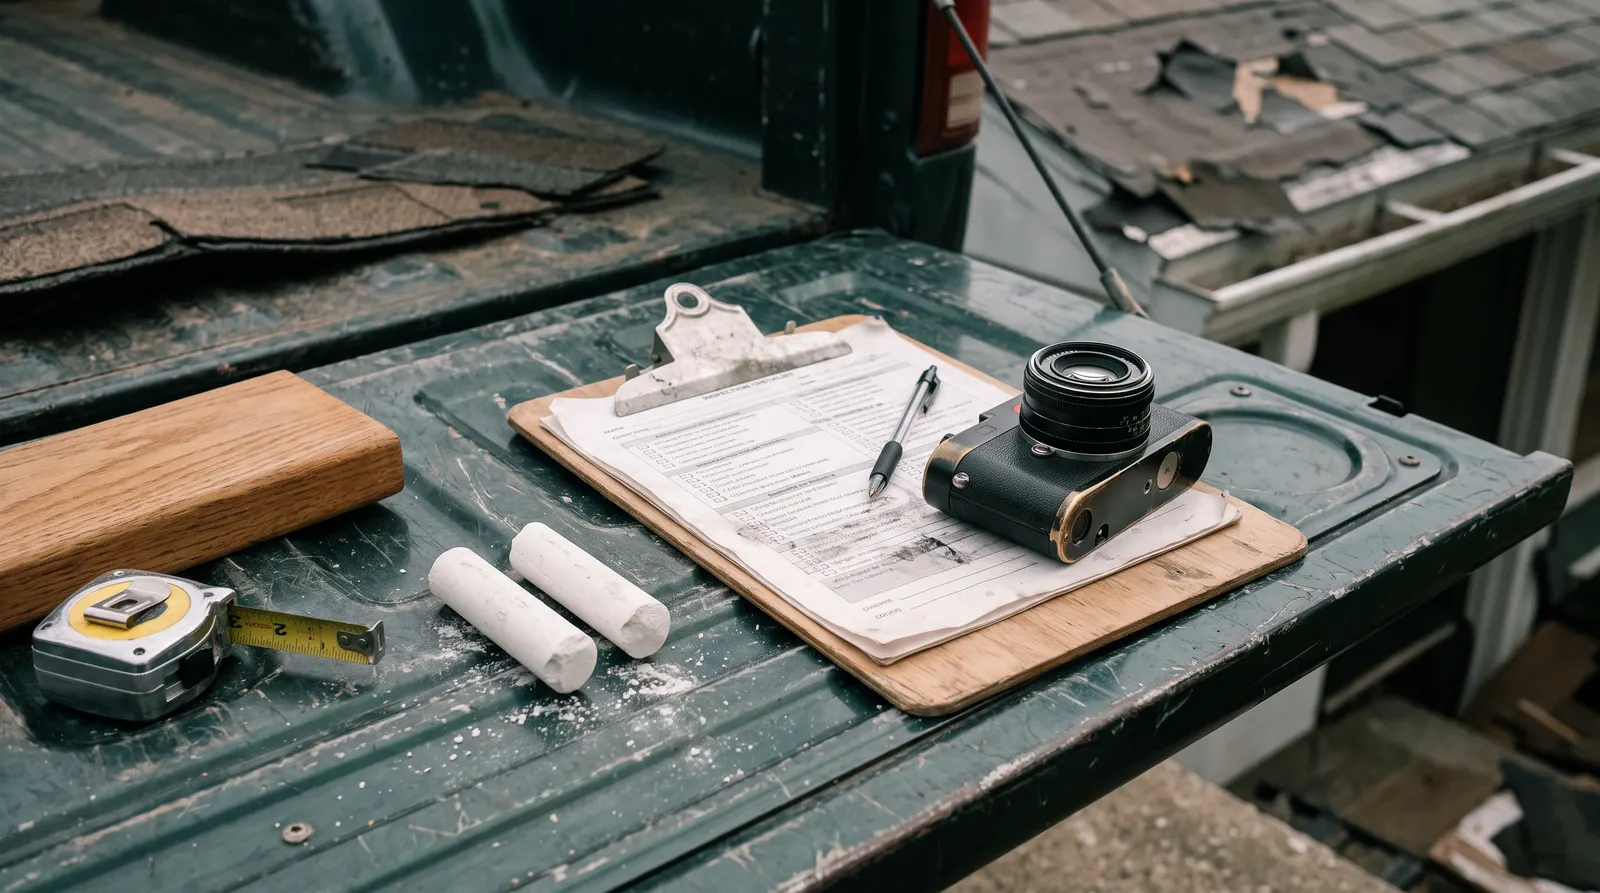
Marking test squares
Photographing to a system
What the adjuster does on the roof
It helps to know what the adjuster is actually doing on the roof, because it is a sampling exercise rather than a hunt for the worst spot.
A roofer from Homestead Roofing describes the method: a ten-foot by ten-foot test square chalked out, usually one on each major roof slope, with the assessment made on the density of hits inside it.
On the hit-count threshold
He does not state the hit-count threshold and we are not going to supply one - it varies by carrier and region.
Two details make photographs read as evidence rather than as advocacy. Fresh hits show black asphalt under the disturbed fibers while older ones have weathered gray, so a date-stamped photo showing black is doing real work.
Mark hits with a dot
One convention worth adopting from the trade: contractors mark hail hits with a small dot rather than a circle, so that the adjuster’s own chalk circles and photographs stay legible and uncontaminated.
How long you have to claim
Report it as soon as you can, because policies require prompt notice and prompt is not defined uniformly.
Deadlines vary by policy and by state, and some carriers apply specific windows to wind and hail claims.
Photograph before you tarp, and photograph the tarp going on. Mitigation without a before-photo is the most common reason a claim gets reduced.
What this stage costs, and what to keep receipts for
Indicative US ranges. Always get a written quote.
Job
Typical range
Notes
Documenting properly
costs nothing
And decides most disputed claims
Emergency tarping, after hours
$1.00–$2.80 / sq ft
Keep the receipt
After-hours call-out fee
$100–$200
Separate line, keep that receipt too
Tree debris removal cover
~$500–$1,000 cap
Where an insured structure was hit
Independent inspection
often free from a local contractor
Worth having before the adjuster visit
Source: Angi 2026 cost to tarp a roof data and Insurance Information Institute guidance on debris removal and claim documentation (retrieved August 2026). Figures vary by region and timing.
Figures last checked
The first row is the point of the page. An hour spent on photographs and notes is the cheapest line in the whole event and frequently the most valuable.
How the matching works, and what we do not do
Emergency Services 24H is a referral service and not an insurance adviser. We do not employ contractors, we do not adjust claims, and we do not act for your insurer.
What happens after you submit
Your request routes to local contractors covering your area, and they contact you directly. Everything on this page is descriptive, and your own policy and adjuster remain the only authority on your claim.
What homeowners actually ask
What people ask, and what nobody answers
Drawn from real public forum threads and reported prices, summarized and attributed as patterns.
These are not reviews of this site, and no names or ratings have been invented.
“What not to say to insurance adjuster roof”
SourceA question homeowners commonly ask about this. It exists because homeowners feel unprepared for that conversation, and none of the top ten guides online prepares them for it.
“How long after a storm can you claim roof damage?”
SourceAnother question homeowners commonly ask. The answer is prompt notice, which varies by policy and by state, and which is why notifying early beats deciding first.
“Document the damage”
SourceThe instruction that appears in essentially every top guide online on storm roof damage, with no list attached to it anywhere. This page is that list.
1 / 3
The adjuster question, answered
The adjuster question is the honest one in that set, and preparation answers most of it. People who arrive at that conversation with organized evidence do not need to worry about phrasing.
Know the line
Safe to check yourself, or call a pro now
Safe to check yourself
Photographing from ground level and from windows
Attic photographs where access is safe and dry
Writing the timeline and call log
Collecting and organizing receipts
Requesting a free contractor inspection
Call a pro now
Any roof access after storm damage
Attic access where the ceiling structure is compromised
Assessing whether decking or framing is damaged
Disputes where the adjuster estimate looks incomplete
Anything involving structural or electrical safety
24/7 dispatch network
Get a local storm damage contractor moving on this
Tell us what happened and where you are. Local contractors covering your area will contact you directly. No obligation to hire, and no obligation to file a claim.
Fire, a gas smell, or an injury? Leave the building and call 911 first, then your gas
utility or power company. Use this form once you are safe.
Straight answers
Frequently asked questions
Short, plain answers to the questions people ask us most about this page.
Does insurance cover roof repair or a full replacement?
Repair when the damage is localized, replacement when it is general across the slope. The adjuster measures test squares to decide which.
What documentation does a storm damage insurance claim need?
Dated photographs of the exterior, the interior and the attic, the storm date, receipts for any emergency work, and the roofing company estimate.
What should I photograph after storm damage to my roof?
Wide shots of each elevation, close shots of missing or creased shingles, gutters and flashing, then interior ceiling staining with something for scale, wet insulation, damaged contents, and the attic including any daylight visible through the decking. Take all of it before any tarp goes on.
Should I document before or after tarping?
Before, always. Temporary protection changes what the adjuster can see, and the photographs taken before it are the evidence that the damage existed and what caused it.
Why does the attic matter for a roof claim?
Because it shows the opening rather than the symptom. Daylight visible through the decking proves a breach, and wet rafters and insulation help establish when the intrusion happened.
What should I write down as well as photograph?
The date and time you first noticed each item of damage, the weather event including any locally reported wind or hail, and a log of every call: who you spoke to, when, and what was agreed. That log is frequently more useful than any single photograph.
How long after a storm can I claim roof damage?
Policies require prompt notice, and what counts as prompt varies by policy and by state. Notify your insurer early even if you have not decided whether to proceed, because a delayed notification is one of the more common reasons a valid claim runs into trouble.
What should I have ready for the adjuster?
Photographs, your written notes and all receipts in one place, and a walk of the property with them rather than a conversation in the kitchen. Ask what is in the estimate and what has been excluded, and ask for that in writing rather than verbally.
The public adjuster row is a percentage of the settlement, not dollars. Worth it on large disputed claims, rarely on small clear ones.
Sources for this page
Insurance Information Institute: What standard homeowners insurance covers, including storm perils and the ~$500 per-item cap on trees, shrubs and plants
Independent, publicly published sources, quoted with attribution and linked in full.
None is affiliated with Emergency Services 24H, reviewed this page, or works in the referral network.
Homestead Roofing, Inc: Roofing contractor and inspector, Colorado Springs, Homestead Roofing - “Roof Inspections After A Massive Hail Storm For Insurance Claims” (Jul 2023)